Finance • August 30, 2026
Why Your Salary Disappears Before Month-End: A Simple Money Leak Audit
You don’t always need a higher salary to feel financially comfortable. Sometimes the bigger problem is that small expenses are quietly consuming your income before you realize where the money went. Here’s a practical way to find those leaks and fix them.
Table of Contents
1. Why a Salary Can Disappear So Quickly
2. The Money Leaks Most People Don’t Notice
3. The 30-Day Money Leak Audit
4. Separate Fixed Costs From Flexible Spending
5. Why Small Expenses Become a Big Problem
6. The Subscription and Auto-Payment Trap
7. Does Easy UPI Spending Make Budgeting Harder?
8. Credit Cards and the Illusion of Extra Money
9. A Realistic Monthly Example
10. A Simple Salary System That Is Easier to Follow
11. Why an Emergency Fund Changes Everything
13. What to Do After Finding Your Money Leaks
14. Quick Monthly Money-Leak Calculator
Why a Salary Can Disappear So Quickly
Getting paid can create a strange feeling. On salary day, your bank balance looks healthy. A few weeks later, you start wondering where the money went.
The problem is often not one huge purchase. It can be a combination of rent, bills, food, transportation, online shopping, subscriptions, small UPI payments, entertainment and unexpected expenses.
Each individual payment may look harmless. The problem becomes visible only when all of them are added together.
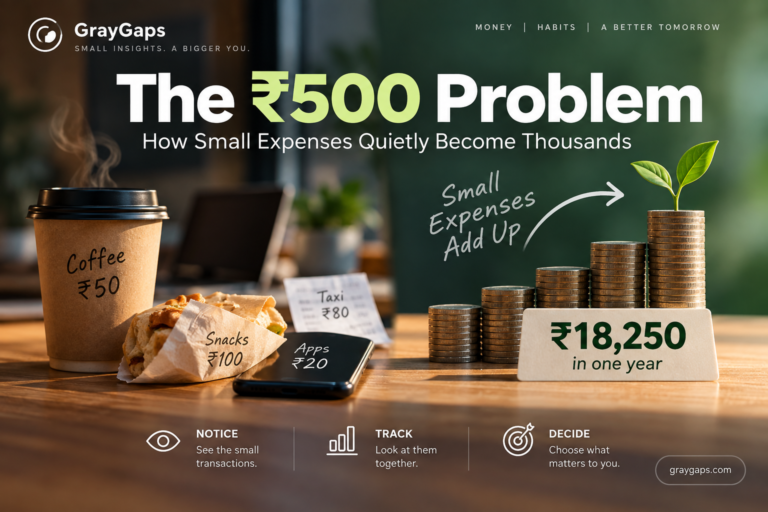
For example, spending ₹150 here, ₹250 there and ₹300 somewhere else doesn’t feel like a major financial decision. But if similar payments happen several times a week, they can become a meaningful part of your monthly income.
The better question is: “What did I spend repeatedly this month?”
The Money Leaks Most People Don’t Notice
A money leak is an expense that repeatedly reduces your available cash without feeling significant at the time.
These expenses aren’t necessarily bad. Having coffee outside, ordering food or paying for entertainment can be perfectly reasonable. The problem occurs when the spending happens automatically and you don’t realize how much it costs over an entire month.
| Possible Money Leak | Why It Gets Ignored | What to Check |
|---|---|---|
| Food delivery | Each order seems manageable | Total monthly spending including delivery charges |
| Subscriptions | Usually paid automatically | Services actually used during the month |
| Online shopping | Small purchases don’t feel expensive | Total non-essential purchases |
| Frequent rides | Convenience makes each trip feel necessary | Total transportation cost |
| Convenience purchases | Low individual value | Repeated daily or weekly spending |
The 30-Day Money Leak Audit
Instead of guessing where your money goes, conduct a simple 30-day audit.
You don’t need a complicated spreadsheet. Your bank statement, UPI transaction history, credit-card statement and cash records are enough to begin.
For every expense, record three things:
- What did I buy?
- How much did it cost?
- Was it planned or spontaneous?
After 30 days, group the expenses into categories. Don’t judge yourself while recording them. The purpose of the first month is to discover your actual behaviour, not to create a perfect budget.
You may be surprised by the results. The category you thought was expensive may not be the biggest problem, while several smaller categories may collectively consume much more money.
Separate Fixed Costs From Flexible Spending
One of the simplest improvements you can make is to stop treating every expense as if it were equally difficult to change.
Rent, loan EMIs and certain essential bills may have limited short-term flexibility. Food delivery, entertainment, shopping and some transportation choices may be easier to adjust.
| Category | Examples | Usually Easier to Change? |
|---|---|---|
| Fixed | Rent, certain EMIs, essential bills | Usually less flexible in the short term |
| Essential but variable | Groceries, electricity, fuel | Sometimes |
| Flexible | Eating out, entertainment, shopping | Often easier |
| Unplanned | Impulse purchases and unexpected discretionary spending | Often the first area to review |
This distinction prevents a common mistake: trying to solve a flexible-spending problem by making unrealistic cuts to essential expenses.
Why Small Expenses Become a Big Problem
Suppose you make an extra ₹200 purchase four times a week. That doesn’t sound like much when you make each payment.
But using a simple four-week calculation:
The calculation isn’t meant to suggest that every small purchase should be eliminated. It demonstrates why frequency matters.
A ₹200 purchase isn’t necessarily the problem. Making dozens of similar decisions without including them in your monthly plan is what creates the problem.
The Subscription and Auto-Payment Trap
Subscriptions are convenient because they remove the need to make the same payment manually every month. That convenience can also make unused services easy to forget.
Go through your bank and card statements and make a list of every recurring payment. Then ask a simple question:
If the answer is no, review whether you still need it.
Don’t cancel useful services simply because they are subscriptions. The goal is to remove payments that no longer provide enough value for you.
Does Easy UPI Spending Make Budgeting Harder?
UPI has made everyday payments extremely convenient. A transaction that once required cash, a card or several steps can now happen in seconds.
That convenience can also make spending feel less significant because the payment process is almost frictionless.
Recent reporting shows how dominant UPI has become in India’s digital merchant payments, while traditional card payments have lost share.
The answer isn’t to stop using UPI. Instead, use your transaction history as a financial record.
At the end of every week, review your UPI payments and total them by category. This creates a small amount of “friction” after spending without removing the convenience of digital payments.
Credit Cards and the Illusion of Extra Money
A credit card can be a useful payment tool, but the available credit limit is not additional income.
If you earn ₹40,000 and have a ₹1,00,000 credit limit, you do not have ₹1,40,000 available to spend safely. The ₹1,00,000 is borrowed purchasing capacity that must eventually be repaid.
The danger becomes greater when the card is used to cover normal expenses that your monthly income cannot comfortably support.
A recent case reported in India illustrated this problem: a high-income earner reportedly lost most of his savings after a combination of family expenses, loans, credit-card spending and unexpected costs created a debt trap.
A Realistic Monthly Example
Consider a hypothetical person earning ₹40,000 per month.
The following example is not a recommended budget. It simply shows how money can disappear through several ordinary categories.
| Expense | Monthly Amount |
|---|---|
| Rent / accommodation | ₹12,000 |
| Food and groceries | ₹7,000 |
| Transport | ₹3,000 |
| Bills and utilities | ₹2,500 |
| Eating out / delivery | ₹3,000 |
| Shopping and entertainment | ₹3,000 |
| Subscriptions and small recurring costs | ₹1,000 |
| Remaining | ₹8,500 |
At first glance, ₹8,500 appears to be a reasonable amount left over. But if additional unplanned purchases consume ₹3,000 to ₹5,000, the person’s effective monthly surplus becomes much smaller.
This is why tracking actual spending matters more than simply knowing your salary.
A Simple Salary System That Is Easier to Follow
A budget can fail even when the mathematics is correct if it is too complicated to follow.
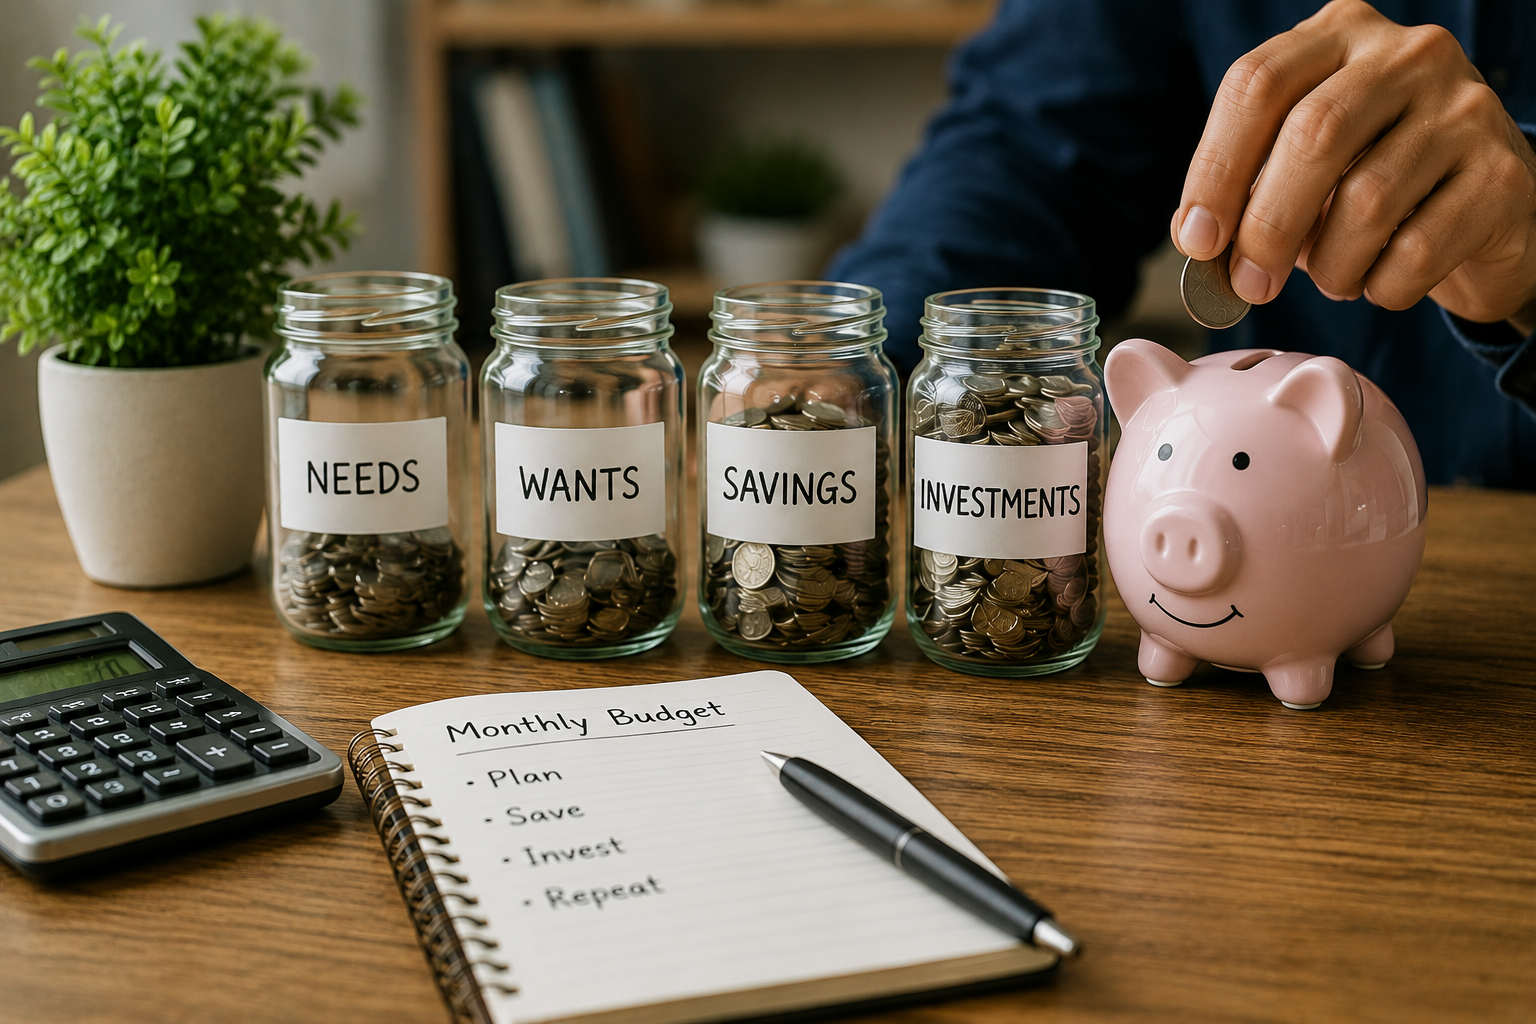
Instead of creating twenty categories, start with a small number of buckets that answer three questions: what must be paid, what can be spent and what should be protected for the future?
1. Essentials — expenses you need to keep your normal life running.
2. Flexible spending — lifestyle expenses you can adjust.
3. Financial goals — emergency savings, debt reduction and long-term investments according to your circumstances.
The exact percentage for each category should depend on your income, rent, family responsibilities, debt and goals. There is no universal percentage that works for everyone.
Why an Emergency Fund Changes Everything
A financial plan can look perfect until an unexpected expense arrives.
Medical expenses, urgent travel, job loss, repairs or family emergencies can create a large financial burden. Without accessible savings, people may have to rely on credit cards, loans or investments that were not intended for immediate spending.
An emergency fund is designed to provide a buffer for such situations.
The appropriate amount depends on your circumstances. Someone with stable employment and low fixed expenses may have different needs from someone supporting a family or working with irregular income.
The important idea is that emergency savings should be treated differently from money intended for everyday spending.
Money Mistakes to Avoid
Fixing your finances doesn’t require extreme behaviour. In fact, some aggressive approaches can make a budget impossible to maintain.
- Trying to eliminate every enjoyable expense.
- Creating a budget based on what you wish you spent rather than what you actually spend.
- Ignoring irregular expenses because they don’t happen every month.
- Treating a credit limit as available income.
- Investing money that may soon be needed for emergencies.
- Taking investment decisions because someone online promises guaranteed returns.
- Continuing a financial plan that clearly doesn’t match your actual income and responsibilities.
SEBI repeatedly warns investors about guaranteed-return claims, unsolicited investment advice and fraudulent social-media schemes.
What to Do After Finding Your Money Leaks
Finding the problem is only the first step. The next step is deciding which leaks are worth fixing.
Don’t try to change everything at once. Look for the expenses that are both frequent and relatively easy to control.
For example, if your audit shows that food delivery costs ₹4,000 a month, you don’t necessarily need to eliminate it. You could set a monthly limit and decide in advance how often you want to order.
The same approach can work for shopping, entertainment and transportation.
The goal is to turn unconscious spending into conscious spending.
A good budget should tell you what you can spend without constantly worrying about whether you are running out of money.
Quick Monthly Money-Leak Calculator
You can calculate the impact of a repeated expense with this simple formula:
For example, if a ₹250 purchase happens three times every week:
That is approximately ₹38,976 over a year if the same pattern continues.
This doesn’t mean the spending must be eliminated. It simply makes the long-term cost visible.
The Difference Between Being Cheap and Being Financially Disciplined
Financial discipline does not mean refusing to spend money.
Someone can spend money on travel, restaurants, hobbies or entertainment and still have good financial habits. The difference is whether those expenses fit within their financial capacity and priorities.
A person earning more money can also have serious financial problems if spending increases every time income increases.
On the other hand, someone with a modest income can make meaningful progress by understanding their cash flow, avoiding unnecessary high-cost debt and consistently protecting some money for future needs.
The objective is not to spend the least. It is to make sure your money is going where you actually want it to go.
Frequently Asked Questions
Why does my salary disappear so quickly?
It may be because several fixed, variable and discretionary expenses are consuming your income without being tracked together. Small recurring purchases can also add up to a significant monthly amount.
How can I find where my money is going?
Review your bank statements, UPI transactions, credit-card statements and cash spending for at least one month. Group the payments into categories and compare the totals.
Should I stop using UPI to save money?
Not necessarily. UPI is simply a payment method. The useful step is to regularly review your UPI transaction history so that convenient payments don’t become invisible spending.
Is a credit-card limit part of my income?
No. A credit limit represents borrowing capacity, not income. Purchases made using credit still need to be repaid.
How much should I save every month?
There is no single percentage that works for everyone. Your appropriate saving amount depends on income, essential expenses, debt, family responsibilities, emergency needs and financial goals.
Should I cut all unnecessary spending?
Not necessarily. A sustainable financial plan should leave room for reasonable lifestyle spending. The goal is to control spending rather than eliminate every non-essential purchase.
Are guaranteed investment returns safe?
A promise of guaranteed or unusually high returns should be treated as a warning sign, particularly in securities-market investments. SEBI advises investors to be cautious of such claims and to verify intermediaries before investing.
What is the first thing I should do if I am always short of money?
Start by tracking every expense for 30 days before making major changes. You need to know whether the main issue is fixed expenses, debt, lifestyle spending, irregular costs or a combination of several factors.
Final Takeaway
If your salary disappears before the month ends, the solution isn’t automatically “earn more” or “spend nothing.” The first step is understanding what is actually happening to your money.
A 30-day spending audit can reveal patterns that are almost impossible to notice when you look at transactions one by one. Once those patterns become visible, you can decide which expenses deserve your money and which ones don’t.
The most useful financial habit may therefore be surprisingly simple: know where your money went before deciding where your money should go next.
And if your financial situation includes significant debt, investments or other complex decisions, consider getting advice from an appropriately qualified professional rather than relying solely on social-media tips or promises of guaranteed returns.
Sources
This article is independently written for GrayGaps. The following sources were used for factual reference and financial-safety information.
-
SEBI Investor — Investor Education and Awareness
-
SEBI Investor — Investor Charter
-
SEBI Investor — Financial Awareness Resources
-
SEBI — Financial Education Booklet
-
Reserve Bank of India
Disclaimer: This article is for general educational and informational purposes only. It is not personalized financial, investment, tax or legal advice. Individual financial circumstances differ, and readers should consider their own situation and seek qualified professional advice where appropriate.
“`
Questions & Answers
Have a question about this article? Ask it below. Other GrayGaps readers can share their experience and help answer it.